Flipping to a U.S. Holding Company: Delaware Incorporation, Shareholders and Contracts

Hello! I’m Noriaki Asato, representative attorney at Legal Agent.
A U.S. investor may offer funding on the condition that the investment be made in a Delaware corporation. Compared with investing directly in the existing Japanese company, this requires management to reorganize ownership as well as negotiate the financing.
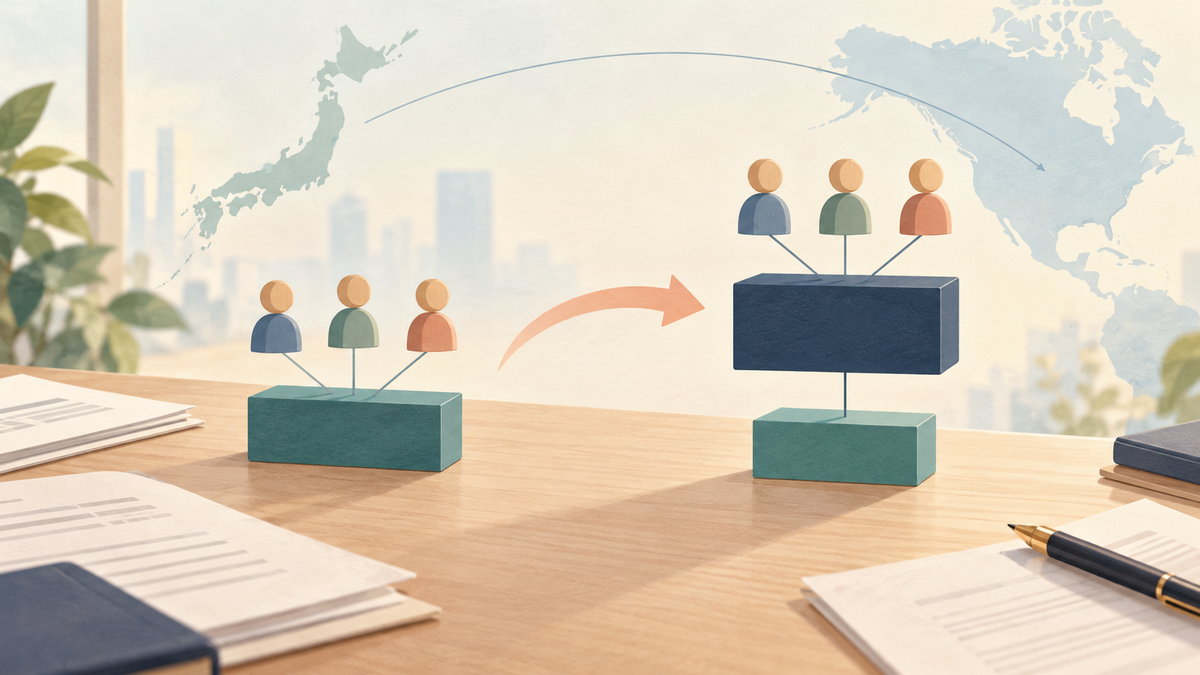
A reorganization in which a U.S. holding company is placed above a Japanese company and the existing shareholders become shareholders of the U.S. parent is commonly called a flip. Incorporating the U.S. entity is only one part of the work. Management needs to examine existing shareholder rights, stock acquisition rights, commercial contracts and tax exposure, then determine whether the transition can be completed before the investment closes.
For companies with numerous shareholders or multiple classes of shares, preserving ownership percentages does not necessarily preserve economic terms. This article examines a Japanese startup’s transition beneath a U.S. holding company, from negotiating the conditions through operating the resulting group.
The purpose of a U.S. holding company and the reorganization method
Management should first establish why the investor requires a U.S. entity and what the investment conditions are. Using U.S. investment documents, raising further capital and conducting business in the United States can call for different arrangements. The procedures also depend on whether the investor must invest in a U.S. parent or whether establishing a U.S. operating subsidiary would suffice.
In a typical arrangement, existing shareholders transfer their Japanese company shares to the U.S. holding company in exchange for shares in that parent. Once all shares have been transferred, the Japanese company becomes a wholly owned subsidiary. The Japanese entity does not disappear and can continue employing staff and conducting business.
The economic description of exchanging shares must be distinguished from a statutory share exchange under Japanese company law. Article 2, item 31 of the Companies Act defines the wholly owning parent in such an exchange as another Japanese stock company or limited liability company. A foreign corporation cannot simply occupy that statutory role in the same manner as a domestic company.
A structure involving contractual acquisitions from individual shareholders and an issuance of U.S. shares requires examination of each shareholder’s agreement and transfer procedures. If other reorganization mechanisms are combined, their particular approvals, consideration and creditor-protection requirements must be considered. Feasibility needs to be checked under both Japanese and U.S. law.
In Delaware, Sections 152 and 153 of the General Corporation Law address stock issuance and consideration. With U.S. counsel, the company should check authorized shares, class rights, consideration and board approvals, and prepare documents that coordinate the U.S. issuance with the Japanese share transfers.
Existing shareholder rights and required consents
Before designing the reorganization, reconcile the shareholder register, capitalization table, articles of incorporation, investment agreements from each round and shareholders’ agreements. A capitalization table alone may not reveal individual investors’ consent rights or special arrangements. Identify the shares and applicable agreements for founders, employee shareholders and investors separately.
For contractual share transfers, a shareholders’ meeting resolution approving the plan does not by itself transfer each shareholder’s shares. Examine the transferring shareholders’ agreements and any applicable tag-along or drag-along provisions. If some shareholders do not transfer, the company may be unable to satisfy an investment condition requiring complete ownership of the Japanese subsidiary.
Where the Japanese shares are subject to transfer restrictions, check the approving body and application and approval procedures under the articles and provisions including Articles 136 and 139 of the Companies Act. If an investment agreement requires prior consent to a reorganization or change of control, obtain it separately from statutory corporate approvals. The consequences of omitting consent depend on the agreement; a repurchase obligation does not arise uniformly in every case.
A comparison of the old and new share terms helps investors evaluate the proposed changes. Ownership percentages are only part of that comparison. Liquidation preferences, conversion rights, dilution adjustments, voting rights, director nomination rights and information rights also matter.
For example, replacing Japanese preferred shares with U.S. common stock can change an investor’s proceeds on a company sale even if the ownership percentage stays the same. Explain dilution from the new financing separately from changes caused by the reorganization. Our articles on investment agreements from the company’s perspective and shareholders’ agreements from the company’s perspective discuss the roles of these contracts.
Stock acquisition rights and rights to future shares
Holding a stock acquisition right does not, by itself, make the holder a current shareholder. Separately from shareholder transfer agreements, review the rights’ issuance terms, allotment agreements and exercise conditions. Employee stock options and financing instruments such as J-KISS must each be handled according to their own terms.
If rights over the Japanese company’s shares remain outstanding, exercising them may create minority shareholders in that company. If the investment requires the U.S. parent to own all Japanese shares, the arrangements must address exercises occurring after the transition as well.
Nor do Japanese stock acquisition rights necessarily become U.S. stock options automatically. For acquiring or extinguishing existing rights and granting new ones, identify the contractual basis, required resolutions and holder consents. J-KISS and similar instruments may contain provisions addressing changes of control or reorganizations; their names alone do not determine the appropriate treatment.
When explaining the transition to employees, compare the underlying shares, exercise price, vesting period, treatment on departure and exercise deadline before and after the change. Granting the same number of rights does not necessarily preserve value or the ownership interest obtainable. Tax-qualified treatment also does not automatically carry over, so the tax review should precede employee explanations.
Tax and foreign exchange review in the closing timetable
A flip should not be planned on the assumption that exchanging shares without receiving cash creates no tax liability. If the transfer is taxable, shareholders may need to find separate cash to pay the tax. Leaving the tax review until the documents are finalized can force changes to the consideration or transaction structure.
The National Tax Agency’s explanation of share exchanges addresses treatment for individual shareholders where specified requirements are satisfied. It does not necessarily apply directly to a transfer beneath a foreign holding company. Tax advisers should be given the shareholders’ individual or corporate status, residence, proposed transaction, share valuations and consideration to assess Japanese and U.S. treatment separately.
The review should cover subsequent dividends, exercises and future sales as well as the initial transfer. A conclusion that Japanese tax is deferred and a conclusion that U.S. nonrecognition requirements are satisfied need separate verification. I believe shareholders should not be told that no tax will arise before the relevant treatment has been established.
Under the Foreign Exchange and Foreign Trade Act, examine the U.S. parent’s acquisition of Japanese shares separately from Japanese residents’ acquisition of foreign shares. As explained in the Ministry of Finance’s guidance on inward direct investment, prior notification, subsequent reporting and related requirements depend on the investor, target business, transaction and availability of exemptions. The fact that a Japanese founder remains the ultimate owner does not necessarily exclude the transaction.
Allow time for required advance notifications and third-party consents. Distinguish the investment agreement’s signing date, the reorganization’s effective date and the new investment’s payment date, and agree which procedures must be completed by each. If the requested timetable cannot be met, discuss changes to deadlines or conditions early.
Commercial contracts and operations after the transition
When the Japanese entity remains in place and only its shareholders change, it will ordinarily remain the party to existing customer and employment contracts. Nevertheless, change-of-control clauses, foreign ownership conditions, subsidy requirements or licensing requirements may apply. Not transferring the contractual position and not needing the counterparty’s consent are separate questions.
Review important license agreements, financing agreements and joint research agreements early because of their effect on business continuity. If intellectual property will move to the U.S. entity, consider assignments or licenses separately from the share transfer. Joint development partner consent, rights acquired from employees and transfer pricing may also require attention.
After the transition, both entities need arrangements for decision-making, accounting, taxation and movement of funds. Decide which company employs staff, contracts with customers and funds research and development, and reflect those responsibilities in intercompany agreements. Budget for maintaining the holding company and the people who will administer it.
If the company later chooses a Japanese listing or another reorganization, simply reversing the original steps may not restore the previous structure. Management therefore needs to weigh the benefits of the proposed investment against continuing administrative costs, business plans and the anticipated exit before selecting the structure.
Services connected to this topic