
VC and CVC Investment SupportFrom reviewing investment and shareholders' agreements to follow-on rounds and the exercise of rights at exit, our attorneys check each step from the investor's side.
- Response time
- 1 business day*
- First consultation
- 30 min free
- Scope
- Investment and shareholders' agreements · DD · Exit
* As a rule, for contract reviews and routine legal questions. For complex or urgent matters we propose a schedule that fits the matter.
Client companies served*
150+Selected clients shown, in no particular order. * Clients and partners. Not limited to VC and CVC Investment Support matters.
Checking investor rights clause by clause
From presenting drafts as lead investor to reviewing agreements presented to you as a follow-on investor, and on to follow-on rounds and exits at existing portfolio companies, we act from the investor's side. We confirm how far the liquidation preference, anti-dilution, prior consent matters, information rights and drag-along and tag-along clauses secure the investor's rights.
- You cannot finalize the contract terms by the investment committee's approval deadline
- You are unsure whether to accept the terms the lead investor negotiated as they are
- You cannot fully calculate how the anti-dilution clause applies in a new round
- You cannot explain to the investment committee the basis for calculating exit distributions
Why LegalAgent
With LegalAgent, you can nail down contract terms from the investor's standpoint
We support your investment decisions in three ways: fast answers, fees you know before we start, and a negotiation strategy suited to your position as lead or follow-on investor.
-
01Speed
Typical law firms
3–5 business daysLegalAgent1 business day, as a rule
We work back from your investment committee schedule
We answer contract reviews and routine legal questions within one business day as a rule. We ask about the terms approved by your investment committee and the planned payment date, and set review priorities accordingly.
-
02Fees
Hourly billing
Total unknown at the startLegalAgentScope and fee set before we start
We quote from the round's size and your position
We ask about the size of the round, whether you are the lead or a follow-on investor and the scope of legal DD, and give you an estimate before we start. Matter-based work is generally on a fixed fee.
-
03Position
- Lead investor
- Follow-on investor
- CVC
Different negotiation strategies for lead and follow-on investors
We take different negotiation approaches depending on whether you draft as lead investor or join as a follow-on investor. For CVCs, we also sort out interests involving the core business.
* Response times are for contract reviews and routine legal questions; they vary by matter.
How it works
The AI Agent organizes the drafts; attorneys set negotiation priorities
The AI Agent organizes the draft agreements and approved terms and extracts the issues; attorneys judge which clauses to push hard for and which you can concede.
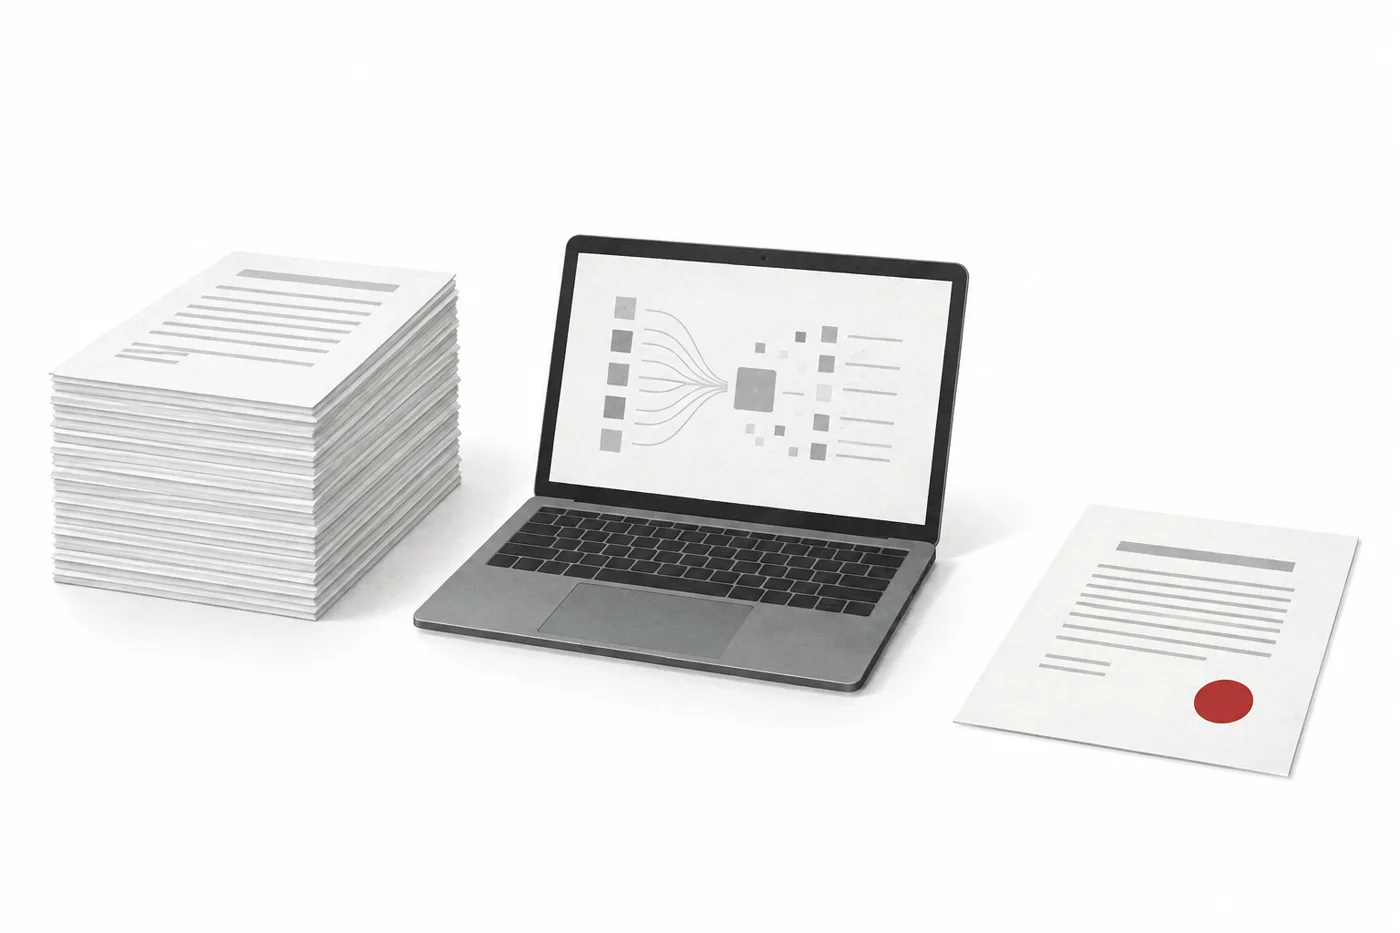
AI Agentdoes the work
- Extracts clauses tied to the approved terms from the drafts
- Draws on existing investment and shareholders' agreements and past clause examples
- Drafts revisions and materials for the investment committee
Attorneysmake the judgment
- Set negotiation priorities from the valuation and round structure
- Determine how anti-dilution clauses and distribution agreements apply
- Take responsibility for the final revisions and negotiation strategy
- STEP 01Confirming the investment terms and your position
Confirm the structure of the round, the participation of other investors and the terms approved by the investment committee, and consider the priorities for review
An approach to reviewing the investment terms and a work plan aligned with the investment committee schedule
- STEP 02Reviewing the agreements and class share terms
Confirm how far the liquidation preference, anti-dilution, prior consent matters, information rights and drag-along and tag-along clauses secure the investor's rights
Clause-by-clause analysis of how investor rights are secured, and proposed revisions
- STEP 03Conducting legal due diligence
Set out the legal issues affecting the investment decision and contract terms, and consider what to reflect in representations and warranties, indemnities and conditions precedent
Legal DD report, list of follow-up questions
- STEP 04Preparing proposed revisions and negotiation strategy
Prepare redlined proposed revisions and a negotiation strategy for the issuing company and other investors
Redlined proposed revisions, negotiation strategy memo
- STEP 05Closing and follow-on support
Confirm whether the conditions precedent to payment have been satisfied, or confirm how rights under existing agreements work in a follow-on round or exit
Closing checklist, or memo on the strategy for exercising rights
- Attorneys make the final callAn attorney checks every deliverable and takes responsibility for it.
- Your inputs are not used to train AIOn top of attorneys' statutory duty of confidentiality, we work in an environment where your inputs are not used to train AI.
- An AI Agent built in-houseOur own engineers develop it. Information Security Policy
Use cases
Common requests and what you receive
From presenting drafts as lead investor to reviewing agreements as a follow-on investor and follow-on rounds and exits at existing portfolio companies, this map shows the consultations that arise at each stage of investment decision-making.
-
01
As lead investor, we need to present drafts of the investment agreement and shareholders' agreement
If left alonePresenting drafts that do not properly build in investor-favorable terms creates a disadvantageous starting point in negotiations with subsequent investors and in coordination within the syndicate
What we doConfirm the round's valuation, investment amount, capital policy and the participation of other investors, and consider the design of the liquidation preference, anti-dilution, prior consent matters and information rights
What you receive- Draft investment agreement
- Draft shareholders' agreement
- Draft class share terms
- Memo on terms for investors
-
02
As a follow-on investor, we need to review agreements presented by the issuing company or the lead investor
If left aloneAgreeing without confirming how far the rights secured by the lead investor extend to follow-on investors may leave involvement in prior consent matters and information rights more limited than expected
What we doFor the drafts presented, confirm who holds prior consent rights, the scope of information rights and the conditions for preemptive rights, and decide whether revisions are needed
What you receive- Memo on whether revisions are needed
- Redlined proposed revisions
- Explanatory materials for the investment committee
-
03
An existing portfolio company is raising its next round, and we want to confirm how our existing rights will work
If left aloneOverlooking the method of applying the anti-dilution clause or the deadline for exercising preemptive rights can lead to dilution of the shareholding or loss of rights
What we doConfirm how the anti-dilution clause, preemptive rights and prior consent matters in the existing investment agreement and shareholders' agreement apply to the new round
What you receive- Analysis of whether to exercise rights
- Requested revisions to the new round agreements
- Memo for internal reporting
-
04
We need to decide on exercising rights under the shareholders' agreement in an exit through the M&A of a portfolio company
If left aloneOverlooking the conditions for drag-along and tag-along clauses or the liquidation preference under the distribution agreement may mean failing to secure the expected return
What we doConfirm the conditions for exercising rights under the shareholders' agreement and distribution agreement, the application of the deemed liquidation clause and the scope of involvement in representations and warranties and indemnities
What you receive- Memo on the strategy for exercising rights
- Materials verifying the distribution calculation
- Explanatory materials for the investment committee
-
05
We need to carry out investor-side legal due diligence before making the investment
If left aloneInvesting without noticing issues in the shareholder structure, change of control clauses in existing contracts, ownership of intellectual property or labor risks means taking on unexpected rights relationships or contingent liabilities
What we doReview the target company's registration, shareholder structure, material contracts, intellectual property and labor materials, and set out the issues to be reflected in the representations and warranties and conditions precedent of the investment agreement and shareholders' agreement
What you receive- Legal DD report
- List of follow-up questions
- List of items to reflect in the investment agreement
Published matters
- BoostCapital / SolafuneServed as legal advisor to BoostCapital
- BoostCapital / IVRyServed as legal advisor to BoostCapital
- BoostCapital / TERASSServed as legal advisor to BoostCapital
- BoostCapital / Driver TechnologiesServed as legal advisor to BoostCapital
- BoostCapital / PleapServed as legal advisor to BoostCapital
Scope of our VC and CVC investment support
We confirm how specifically investor-side rights are reflected in the agreements, and set out the judgments and deliverables for each investment stage.
- Review and negotiation of investment agreements and shareholders' agreements
- Whether you are the lead investor or a follow-on investor, we confirm that investor rights are specifically reflected in the agreements.
- Review and revision of investment agreements
- Review and negotiation of shareholders' agreements
- Review of class share terms
- Investor-side legal due diligence
- Before the investment is made, we set out the legal issues to be reflected in the investment decision and the contract terms.
- Conducting legal DD
- Reflecting DD results in the agreements
- Analysis of issues specific to CVCs
- For CVC investments that involve a relationship with the core business, we organize business synergy clauses and competitive relationships.
- Analysis of business synergy clauses and competitive relationships
- Decisions on exercising rights in follow-on rounds and exits
- In additional fundraising by existing portfolio companies and at the M&A or IPO stage, we set out how to exercise contractual rights.
- Confirming rights in follow-on rounds
- Decisions on exercising rights at exit
Our approach
What we focus on in VC and CVC Investment Support
In VC and CVC investment matters, we place weight on the following perspectives.
- 01
Judging negotiation priorities in light of valuation and round structure
Based on the valuation, capital policy and participation of other investors, we distinguish, within the design of the liquidation preference and anti-dilution, the clauses the investor should push hard for from those it can concede.
- 02
Adjusting the design of rights to the lead or follow-on position
We consider negotiation strategies for prior consent matters and information rights separately for drafting the agreements as lead investor and for joining existing agreements as a follow-on investor.
- 03
Balancing interests with the core business in the case of CVCs
For CVC investments where transaction terms and the scope of information sharing with the portfolio company overlap with the interests of the core business, we consider how to build these into the investment agreement and shareholders' agreement while taking antitrust considerations into account.
- 04
Clause design that looks ahead to post-investment follow-on rounds and exits
We review the clause wording and conditions of application with an eye not only on the terms at the time of investment but also on the effect of the anti-dilution clause in the next round and the distribution calculation at exit.
Pricing
VC and CVC investment support fees
For consultations on reviewing investment agreements and shareholders' agreements and on legal due diligence, we provide an estimate after hearing about the size of the round and the scope of review.
How fees are set
Scope and fee agreed before we startMatter-based work is generally on a fixed fee. For complex or urgent matters, we propose a schedule and an estimate that fit the matter.
First consultation
A free 30-minute online meeting.You can come to us before your documents are in order. Tell us what you know so far.
Free consultationWhat we check before quoting
- Size of the round and type of security (preferred shares, J-KISS, etc.)
- Whether you are the lead investor or a follow-on investor
- Scope of legal due diligence (document review only, or including Q&A and a written report)
- Number of rounds of contract negotiation and time until the investment is made
- Whether ongoing review is needed in follow-on rounds and exits
Terms and the scope of review differ for each round, so we provide an individual estimate based on the details of your consultation.
Team & Record
Attorneys who know M&A and financing handle your matters
- Financing matters
- 65Since 2024, issuer and investor side
- Legal and investment DD
- 20+
- Startup legal matters
- 200+
- Contract reviews and drafts
- 2,000+
* Approximate figures based on matters handled by our firm; actual figures vary by matter.
 Founders · M&A · FundraisingNoriaki AsatoRepresentative Attorney / Founder & CEO / Dai-ichi Tokyo Bar Association
 Startup legal · Contract operations DX · Business development experienceTakashi SugaiAttorney / Corporate Legal Practice / Daini Tokyo Bar Association
 Intellectual property · Patent disputes · Japan Patent Office secondmentKosuke HirukawaAttorney / Intellectual Property Practice / Tokyo Bar Association
Engineers
Shinya Makita and Sota Miya build our product on the same team as the attorneys.
Practical guides for investors
- Designing the Terms of Preferred Shares: Liquidation Preference, Conversion and Down-Round Adjustment
- What Is an Investment Agreement? Key Provisions, Differences from the Shareholders' Agreement, and Points for the Issuing Company to Check
- What Is a Shareholders' Agreement? Purpose, Key Provisions, Differences from the Investment Agreement, and Post-Signing Operation
- What Is a Distribution Agreement? Practical Issues of Distribution on M&A and Deemed Liquidation Clauses
- Convertible Notes vs. J-KISS: Repayment Obligations, Maturity and Conversion Terms
FAQ
Frequently asked questions
Can we consult you before there is a draft investment agreement?
You can consult us from the stage after the terms are settled at the investment committee and before the agreements are presented to the issuing company. We will hear the expected valuation and investment terms and set out the direction for clause design.
As a follow-on investor, can we engage you only to review agreements that are already finalized?
We also accept engagements limited to reviewing investment agreements and shareholders' agreements prepared by the lead investor. We focus on how far prior consent matters and information rights extend to your firm as a follow-on investor.
Can we engage you only for investor-side legal due diligence?
We also accept engagements for legal DD alone. We conduct the review with an eye on which clauses of the investment agreement and shareholders' agreement the DD results should be reflected in.
Can we also engage you for fund formation or preparing an LPA?
Formation of the fund itself, LPAs and LLP agreements, and notifications for specially permitted businesses for qualified institutional investors are handled on the Fund Formation page. This page covers the execution, management and exit of individual investments.
Do you also handle acquisitions of all the shares of a portfolio company?
Entire M&A transactions aimed at acquiring control of a portfolio company are handled on the M&A Support page. This page covers investment agreements and shareholders' agreements as a minority shareholder and decisions on exercising rights at exit.
As a CVC, can we consult you about reflecting synergies with our core business in the clauses?
Yes, you can consult us on building business alliances and the scope of information sharing between the core business and the portfolio company into the investment agreement and shareholders' agreement. We organize these together with antitrust considerations.
In an existing portfolio company's new round, can we ask you only to confirm how the existing anti-dilution clause works?
We also accept engagements limited to confirming the effect of existing clauses, without revising the agreements.
Can we consult you from the point when an exit through the M&A of a portfolio company has been decided?
You can consult us from the stage when the acquisition price has been presented. We confirm the calculation of distributions under the distribution agreement and the response to drag-along and tag-along clauses.
Contact
Tell us about your investment round
Please share the information known at this point, such as an overview of the round, draft agreements and the investment committee's approval conditions.
- A free 30-minute online first meeting
- You can consult us before you present a draft agreement
- You can ask us only to confirm how existing clauses apply