
Fund FormationFrom choosing the vehicle to drafting the LPA, negotiating with LP investors and checking whether the specially permitted business notification is needed, our attorneys handle it all as one engagement.
- Response time
- 1 business day*
- First consultation
- 30 min free
- Scope
- Vehicle · LPA · Notification check · Amendments
* As a rule, for contract reviews and routine legal questions. For complex or urgent matters we propose a schedule that fits the matter.
Client companies served*
150+Selected clients shown, in no particular order. * Clients and partners. Not limited to Fund Formation matters.
Fund terms designed around your investor composition
After confirming your investment targets, the investor composition you envisage and your management structure, we choose a vehicle such as an investment limited partnership under the LPS Act or an LLP, and build management fees, carried interest, key person clauses and investment restrictions into the LPA. We also check case by case, based on the investors' attributes and how they will be solicited, whether measures such as the notification of specially permitted business for qualified institutional investors are needed.
- You cannot explain to investors why you chose the vehicle
- You are unsure how far to accept individual terms from LP investors
- Investor solicitation is under way without checking whether notification is needed
- You are unsure whether your second fund can reuse the first fund's terms as they are
Why LegalAgent
With LegalAgent, you can form the fund on a schedule worked back from the start of operations
We support your fund launch in three ways: fast answers, upfront fee estimates and terms designed from both the GP and LP perspectives.
-
01Speed
Typical law firms
3–5 business daysLegalAgent1 business day, as a rule
Steps planned back from the start of operations
For contract reviews and routine legal questions, we respond within one business day as a rule. For fund formation, we work back from the date you want operations to start and map out the necessary steps and schedule at the first consultation.
-
02Fees
Hourly billing
Total unknown at the startLegalAgentScope and fee set before we start
Fees based on your scheme and investor composition
We ask about the type of vehicle, the scope of negotiations with LP investors and whether the LPA is drafted from scratch or amended, and give you an estimate before we start. Matter-based work is generally on a fixed fee.
-
03Both sides
- Management fees
- Carried interest
- Key person clauses
- Investment restrictions
Terms checked from both the GP and LP sides
We work out the terms for management fees and carried interest, taking into account both the GP's operational flexibility and the monitoring and reporting mechanisms LP investors require.
* Response times are for contract reviews and routine legal questions; they vary by matter.
How it works
The AI Agent drafts; attorneys decide the terms and whether notification is needed
The AI Agent organizes the materials you provide and drafts the LPA; attorneys design the management fee and carried interest terms and decide whether the specially permitted business notification or similar measures are needed.
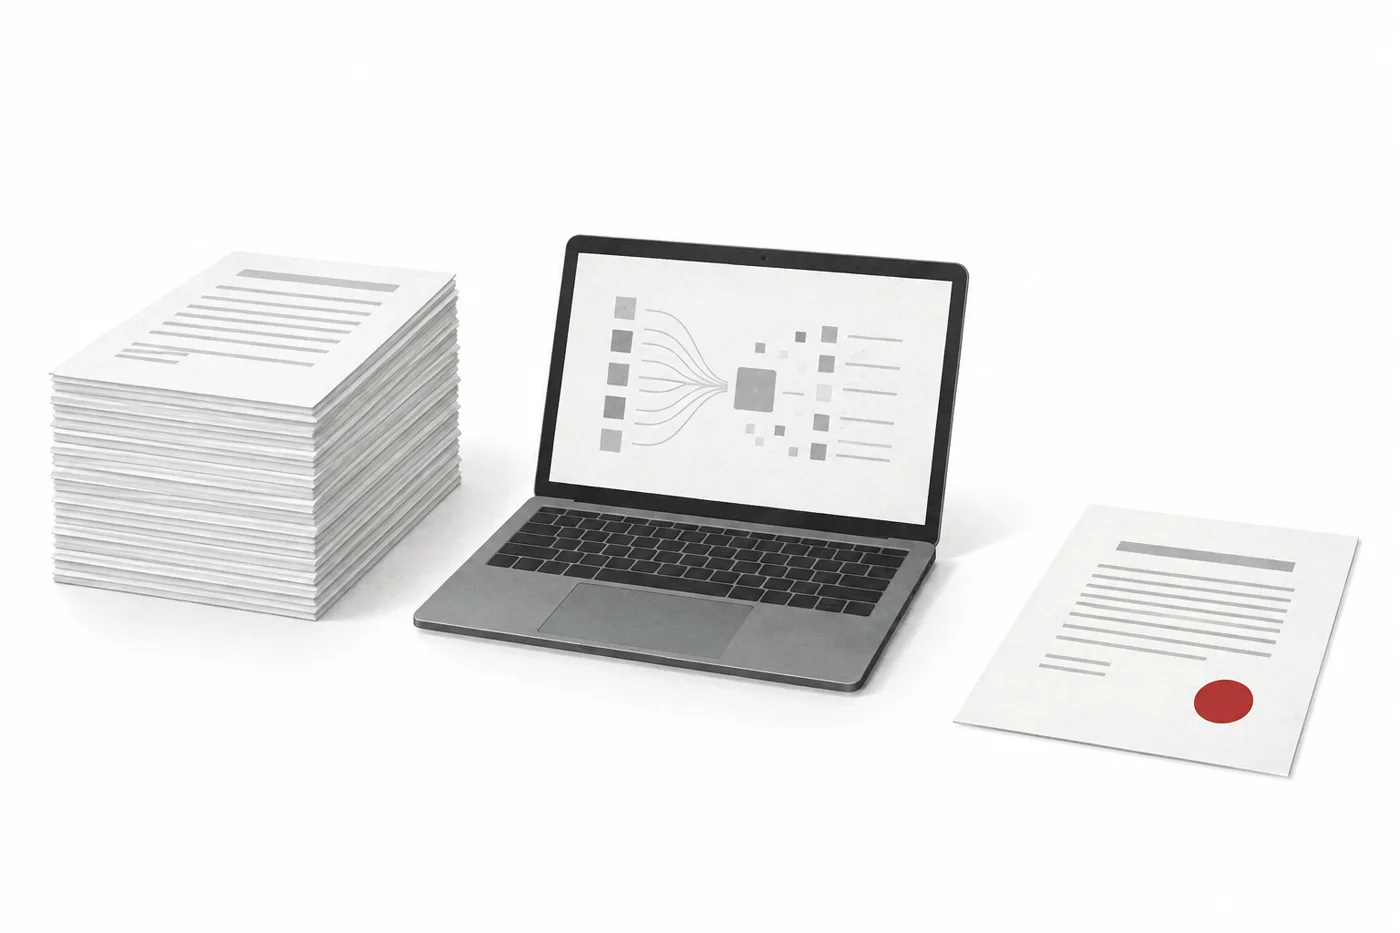
AI Agentdoes the work
- Extracts issues from materials on investment policy and investor composition
- Draws on past clause examples and LPA templates
- Drafts the LPA and side letters
Attorneysmake the judgment
- Decide on the vehicle and the design of management fees and carried interest
- Judge whether the specially permitted business notification or similar measures are needed
- Take responsibility for the final LPA and how to respond to investors
- STEP 01Confirming the investment scheme and investor composition
We confirm the investment scheme and investor composition, and organize the issues in choosing a vehicle such as an investment limited partnership or LLP
Scheme memo and issue summary on vehicle selection
- STEP 02Designing LPA terms and drafting
We organize the terms from the perspectives of both GP and LP and draft the LPA
LPA draft and issue list by clause
- STEP 03Confirming Financial Instruments and Exchange Act measures
We confirm whether Financial Instruments and Exchange Act measures, such as the specially permitted business notification, are needed
Regulatory confirmation memo
- STEP 04Handling term negotiations with LP investors
We confirm fairness to other LP investors and consistency with the overall fund design, and organize the negotiation strategy
Draft LPA revisions, draft side letter and memo on the response policy to investors
- STEP 05Preparing documents for establishment procedures and registration
We organize the documents needed for entering into the partnership agreement and registration
Establishment document checklist and drafts of required documents
- Attorneys make the final callAn attorney checks every deliverable and takes responsibility for it.
- Your inputs are not used to train AIOn top of attorneys' statutory duty of confidentiality, we work in an environment where your inputs are not used to train AI.
- An AI Agent built in-houseOur own engineers develop it. Information Security Policy
Use cases
Common requests and what you receive
From forming a fund for the first time as a GP to consultations arising during the operation of an existing fund, we separate our support by starting point.
-
01
You have decided to form a first fund but have no LPA template and do not know where to start
If left aloneDrafting the LPA without reflecting the investor composition or investment policy means rebuilding the terms later during investor presentations and negotiations
What we doAfter confirming the investor composition, investment targets, management structure and the design of management fees and profit distribution, we select the vehicle and translate the design into an LPA draft
What you receive- LPA draft
- Scheme memo
- Issue summary for investor presentations
-
02
LP investors have sent requests to revise management fees, carried interest or key person clauses
If left aloneAgreeing to different terms with individual LP investors undermines fairness among LP investors and consistency with the existing LPA
What we doWe analyze how far the requests can be accommodated in light of the overall LPA term design and the relationship with side letters
What you receive- Draft LPA revisions
- Draft side letter
- Memo on the response policy to LP investors
-
03
You want to confirm whether the notification of specially permitted business for qualified institutional investors is needed and how to proceed
If left aloneProceeding with solicitation and management without confirming whether notification is needed requires the structure to be revised later
What we doBased on the envisaged investor composition and management structure, we confirm whether Financial Instruments and Exchange Act measures, such as the specially permitted business notification, are needed
What you receive- Regulatory confirmation memo
- Issue summary on required documents and structure
-
04
As a CVC, you are considering moving from balance sheet investment to a fund structure
If left aloneMoving to a fund structure with the same decision-making process as balance sheet investment means operations start without organizing the duties as GP or accountability to LP investors
What we doWe review the operating company's decision-making structure and the fund's governance design, and organize consistency between the GP's duties and the internal approval process
What you receive- Fund design memo
- LPA draft
- Internal structure materials
-
05
Based on the operation of the first fund, you are considering forming a second fund or amending the existing LPA
If left aloneForming a fund on the same terms without reflecting the first fund's track record or investor feedback leads to requests to revise terms at the investor solicitation stage
What we doBased on the first fund's operating status and feedback from LP investors, we identify where terms need to change and the scope of the impact
What you receive- Amended LPA draft
- Table of changes
- Investor explanatory materials
Scope of our fund formation support
After confirming the reasons for the vehicle choice, the LPA term design and whether Financial Instruments and Exchange Act measures are needed, we support you from establishment through operations after launch.
- Fund scheme and vehicle selection
- Based on the investment targets, management structure and investor composition, we select a vehicle such as an investment limited partnership or LLP and organize the overall scheme.
- Organizing the investment scheme and vehicle
- Designing terms for management fees, carried interest and profit distribution
- LPA drafting and negotiations with LP investors
- We support everything from drafting the LPA to term negotiations with each LP investor and handling side letters.
- Drafting the LPA (partnership agreement)
- Handling term negotiations with LP investors
- Financial Instruments and Exchange Act measures such as the specially permitted business notification, and establishment procedures
- Based on the envisaged investor composition and management structure, we confirm whether Financial Instruments and Exchange Act measures are needed and prepare documents for establishment and registration.
- Confirming whether the notification of specially permitted business for qualified institutional investors or similar measures are needed
- Preparing documents for establishment procedures and registration
- Partnership operations and agreement amendments after launch
- We organize issues relating to agreement amendments after the fund begins operating, forming a second fund and running the investment committee.
- Support for amending existing LPAs and forming second funds
Our approach
What we focus on in Fund Formation
In fund formation, we focus on the following perspectives.
- 01
Reviewing LPA terms from the perspectives of both GP and LP
We review the design of management fees, carried interest and key person clauses in light of both the GP's need for operational flexibility and the monitoring and reporting mechanisms that LP investors require.
- 02
Confirming Financial Instruments and Exchange Act measures individually according to the investor composition
Because the attributes and number of envisaged investors differ from matter to matter, we do not make blanket judgments, but confirm whether the specially permitted business notification or similar measures are needed in light of the envisaged solicitation method and management structure.
- 03
Reflecting the first fund's track record in the term design of second and subsequent funds
After reviewing the operating status of the existing fund and feedback from LP investors, we organize how these should be reflected in the term design of the next fund or in agreement amendments.
- 04
Aligning the operating company's decision-making process with fund governance
Where a fund structure is adopted as a CVC, we confirm consistency between the parent's internal approval process and the speed of decision-making as GP and the design of the investment committee's authority.
Pricing
Fund formation fees
For fund formation consultations, we provide an estimate after hearing about the investment scheme and investor composition.
How fees are set
Scope and fee agreed before we startMatter-based work is generally on a fixed fee. For complex or urgent matters, we propose a schedule and an estimate that fit the matter.
First consultation
A free 30-minute online meeting.You can come to us before your documents are in order. Tell us what you know so far.
Free consultationWhat we check before quoting
- The type of vehicle, and whether the LPA is newly drafted or an existing LPA is amended
- The envisaged number of investors and the expected number of negotiation rounds with LP investors
- The scope of confirmation of Financial Instruments and Exchange Act measures such as the specially permitted business notification
- Whether the preparation of documents for establishment procedures and registration is included
- Whether ongoing support, such as forming a second fund or amending the agreement, is needed
Because the scope of review differs greatly depending on the investment scheme and investor composition, we provide an individual estimate after hearing the details.
Team & Record
Attorneys who know M&A and financing handle your matters
- Financing matters
- 65Since 2024, issuer and investor side
- Startup legal matters
- 200+
- Contract reviews and drafts
- 2,000+
- Client companies
- 150+
* Approximate figures based on matters handled by our firm; actual figures vary by matter.
 Founders · M&A · FundraisingNoriaki AsatoRepresentative Attorney / Founder & CEO / Dai-ichi Tokyo Bar Association
 Startup legal · Contract operations DX · Business development experienceTakashi SugaiAttorney / Corporate Legal Practice / Daini Tokyo Bar Association
 Intellectual property · Patent disputes · Japan Patent Office secondmentKosuke HirukawaAttorney / Intellectual Property Practice / Tokyo Bar Association
Engineers
Shinya Makita and Sota Miya build our product on the same team as the attorneys.
FAQ
Frequently asked questions
Can we consult you before the investment scheme has been settled?
You can consult us from the stage of considering the investment targets and investor composition. We support you from organizing the issues in vehicle selection and term design.
What materials are needed for a fund formation consultation?
Please prepare materials showing the investment targets, investment policy, envisaged investors and contribution amounts, the GP's management structure, desired terms for management fees and carried interest, and the desired start date of operations. If you have no LPA template, we draft one after reviewing this information.
How long does it take to form a fund?
The time required varies with the type of vehicle, the LPA term design, the number of negotiation rounds with LP investors, and whether registration and notification are needed. Working back from the desired start date of operations, we organize the necessary steps and schedule at the initial consultation.
How is the cost of forming a fund determined?
We provide an estimate based on the type of vehicle, whether the LPA is newly drafted or an existing template is amended, the number of LP investors and the scope of negotiations, the notification work, the types of documents required and whether ongoing support is needed after establishment.
Can you confirm only whether the specially permitted business notification is needed?
We also handle consultations limited to confirming whether the specially permitted business notification or similar measures are needed. Whether to proceed to the details of the requirements or the notification procedure itself can be discussed again based on the results of the confirmation.
Can we engage you only to amend an existing LPA or form a second fund?
Not limited to forming new funds, we also handle consultations on amending existing LPAs and forming second funds.
After the fund is formed, can we also engage you for contracts for individual investments in portfolio companies?
Drafting investment agreements and shareholders' agreements and conducting due diligence for individual investments are handled on the startup investor-side (VC and CVC) support page. Please see that page as well as your fund formation consultation.
How will you handle requests from LP investors to revise terms?
After analyzing how the requests affect the overall LPA term design and fairness to other LP investors, we prepare a response policy and draft LPA revisions or a draft side letter.
Contact
Tell us about the fund you have in mind
Please let us know the investment targets, the envisaged investor composition and any preferences on terms that you have at this point.
- A free 30-minute online first meeting
- You can consult us before your investment scheme is settled
- You can ask us only to check whether the specially permitted business notification is needed